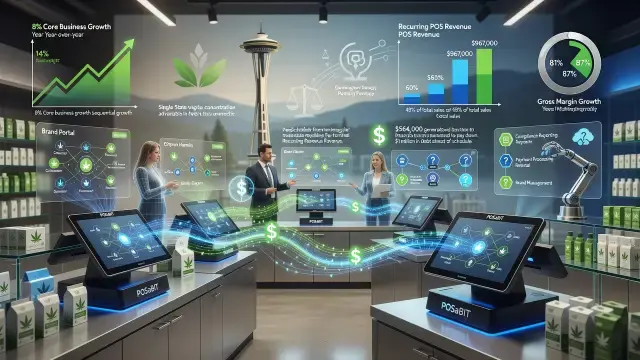
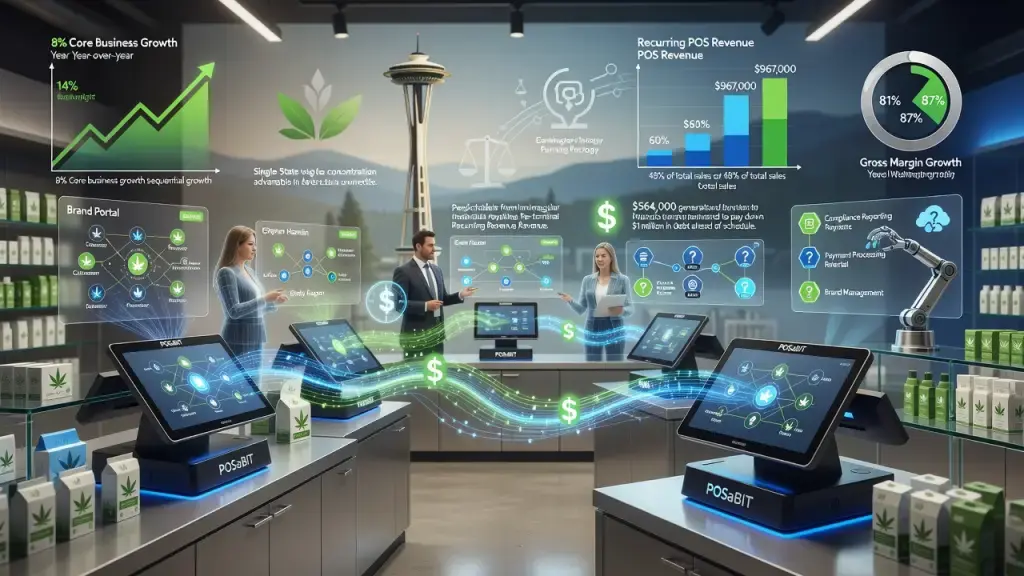
POSaBIT Systems posted a quarter that looks worse on the surface than it actually is. Total revenue slipped 2% year over year to $2.3 million, but that decline traces almost entirely to a single contract shift - a licensing deal that moved from a monthly royalty to a per-terminal structure. Strip that out, and the cannabis point-of-sale vendor's core business grew 8% year over year and 14% sequentially, with gross margin expanding to 87% from 81% a year ago.
A Deliberate Trade: Less Headline Revenue, Better Revenue
Here's the catch with licensing income: it's often lumpy, front-loaded, and not particularly predictable quarter to quarter. POSaBIT's old monthly royalty arrangement generated outsized cash in prior periods, but it wasn't the kind of revenue a software company can build a multiple on. The shift to a usage-based, per-terminal royalty shrinks that line item going forward - CFO Emily Eagon called the adjusted EBITDA decline "a contract timing story" - but it also forces the business to stand on its own operating fundamentals.
Those fundamentals held up. Point-of-sale revenue reached $1.1 million, or 48% of total sales, up 39% year over year. More telling: recurring POS revenue, which excludes one-time hardware sales, climbed roughly 60% to $967,000. For a POS vendor in a regulated, cash-intensive retail category like cannabis, recurring software and payment-adjacent revenue is the metric that actually signals durability. Hardware sells once; SaaS subscriptions and payment referrals bill every month.
Washington State Concentration: Strength and Exposure
POSaBIT's strategy is openly concentrated rather than diversified. Management has chosen to dominate a single state's cannabis retail ecosystem - point-of-sale terminals, seed-to-sale-adjacent data flows, and now a Brand Portal connecting producers and processors to retailers - rather than spread thin across a dozen adult-use markets the way some competitors do. CEO Ryan Hamlin framed this as a data-ownership play: controlling transaction data from cultivator to dispensary counter, he argued, becomes more valuable as AI tools are layered on top of retail analytics.
That logic has merit. A vendor that owns the full transaction chain in one market can cross-sell payment processing, compliance reporting, and brand analytics more efficiently than a company juggling fragmented footprints across states with different seed-to-sale tracking mandates and tax regimes. But concentration is still concentration. Any regulatory shift in Washington - license cap changes, excise tax adjustments, or new testing and packaging rules - would hit POSaBIT harder than a geographically diversified competitor.
Cash Generation and the 280E Backdrop
Operating loss narrowed to $123,000 from $511,000, and net loss improved to $118,000 from $596,000. The company generated $564,000 in operating cash flow during the quarter and used part of it to pay down $1 million of debt ahead of schedule while renegotiating better terms. For a sector still squeezed by Section 280E's disallowance of standard business deductions for plant-touching operations, cash generation at the software and payments layer - which typically sits adjacent to, rather than inside, the 280E trap - matters more than it might in an ordinary tech company.
Management said it is weighing reinvestment, a dividend, or other capital allocation options, including a go-private scenario. No decision has been made. That's worth watching: a small-cap vendor moving from survival mode to optionality is a meaningful signal for the point-of-sale and payments segment of cannabis retail technology, where many providers still operate on thin margins and uncertain banking access.
What Dispensary Operators and Vendors Should Take From This
- Recurring software and payment-referral revenue is becoming the preferred growth metric for cannabis retail tech vendors, not one-time hardware or licensing deals.
- Gross margin expansion tied to processing-cost elimination suggests cashless and compliant payment infrastructure is maturing in at least some state markets.
- Single-state dominance strategies carry real advantages in data integration and cross-selling, but they also concentrate regulatory and market risk.
- AI-driven tools querying POS and brand data are moving from novelty to standard feature set for dispensary back-office and wholesale brand management.